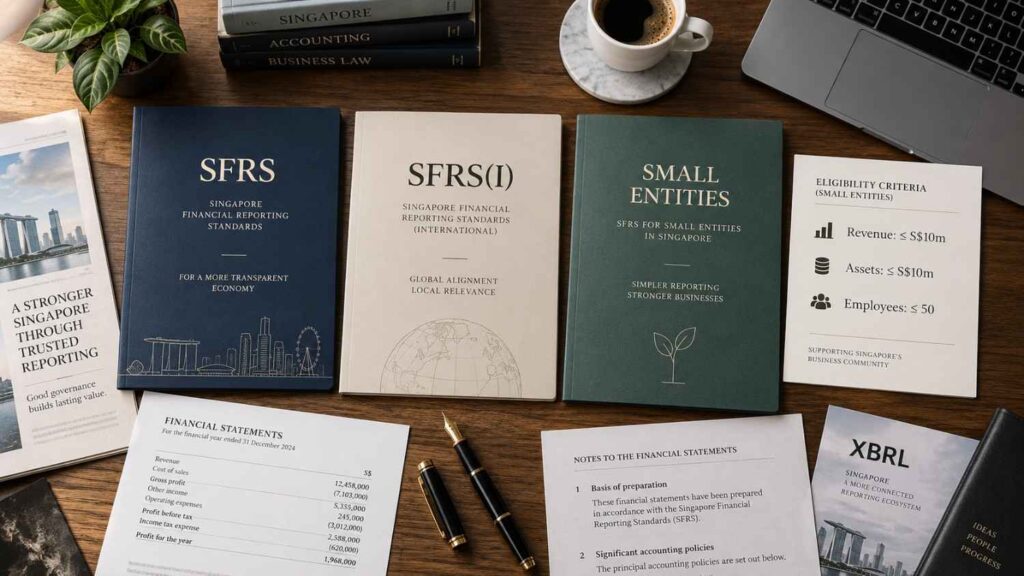
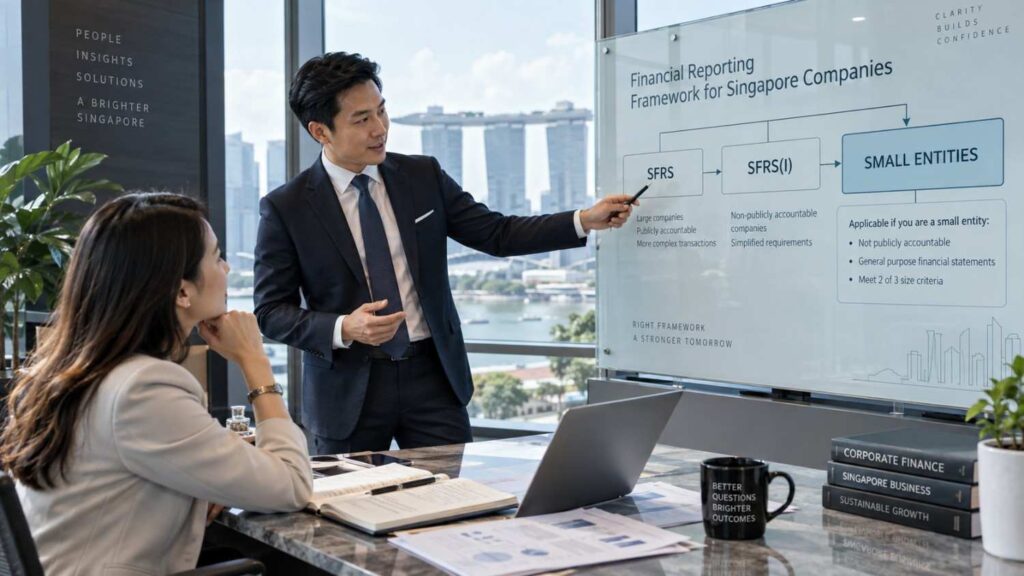
Singapore-incorporated companies prepare financial statements under Singapore Financial Reporting Standards (SFRS). Companies that need statements compliant with international standards, including listed companies, apply SFRS(I). Smaller companies that are not publicly accountable may instead apply the SFRS for Small Entities if they meet at least two of three criteria: total annual revenue not exceeding S$10 million, total gross assets not exceeding S$10 million, and not more than 50 employees. The framework you use is named in your audit report and determines your XBRL filing route.
The reporting framework is a decision most SMEs never consciously make. It gets made for them, usually by whoever prepared the first set of accounts, and then it persists for a decade. That is a shame, because for a company under the size thresholds the choice has a real effect on how much disclosure work has to be done every year. This article explains the three frameworks, who qualifies for the lighter one, and what the choice changes downstream.
The three frameworks
| Framework | Who it is for | In short |
| SFRS | The default for Singapore-incorporated companies | The full set of Singapore Financial Reporting Standards, closely aligned with IFRS |
| SFRS(I) | Companies that need financial statements compliant with International Financial Reporting Standards, including listed companies and those reporting into international groups | Identical in substance to IFRS, allowing an explicit statement of compliance with IFRS |
| SFRS for Small Entities | Smaller companies that are not publicly accountable and meet the size criteria | A substantially reduced standard with simpler recognition, measurement and disclosure requirements |
All three are issued under the authority of the Accounting Standards Committee. They are alternatives, not a hierarchy of quality: a company applying SFRS for Small Entities is not producing lesser financial statements, it is producing financial statements calibrated to a smaller entity and a narrower group of users.
 Who qualifies for SFRS for Small Entities
An entity is eligible to apply the SFRS for Small Entities if it meets all of the following:
- It is not publicly accountable
- It publishes general purpose financial statements for external users
- It meets at least two of the three size criteria below
| Size criterion | Threshold |
| Total annual revenue | Not more than S$10 million |
| Total gross assets | Not more than S$10 million |
| Total number of employees | Not more than 50 |
Publicly accountable is the condition that disqualifies companies most often, and it is broader than being listed. An entity is publicly accountable if its debt or equity instruments are traded in a public market, or if it holds assets in a fiduciary capacity for a broad group of outsiders as one of its primary businesses. That second limb captures banks, insurers, securities dealers and certain fund managers regardless of size.
The thresholds will look familiar, because they are the same numbers used for the small company audit exemption in the Companies Act. They are not the same test, though: the audit exemption test has its own conditions about consecutive financial years and about groups. A company can be eligible for one and not the other.
What actually changes if you apply SFRS for Small Entities
The savings are concentrated in disclosure and in the more complex measurement areas. Broadly:
- Disclosure requirements are substantially shorter, which is where most of the annual preparation time goes
- Financial instruments are dealt with under a simpler model than the full expected credit loss approach
- Goodwill is amortised rather than tested for impairment annually, removing a recurring valuation exercise
- Development costs and borrowing costs are expensed rather than capitalised
- Investment property and property, plant and equipment revaluation options are more restricted
- There is no requirement to present the range of alternative performance information that the full framework calls for
For a company with straightforward operations, the difference across a year is measured in preparation effort rather than in reported profit. For a company with intangibles, complex financial instruments or revalued property, the differences are more substantive and worth modelling before switching.
Why the framework appears in your audit report
An audit opinion is not an opinion in the abstract. It states whether the financial statements give a true and fair view in accordance with a named framework. That framework is written into the report.
Two practical consequences follow. First, the auditor tests compliance against the framework you selected, so choosing SFRS for Small Entities does not reduce the rigour of the audit, only the volume of disclosure being checked. Second, if the financial statements were prepared under one framework and the report names another, that is an error in the report, not a technicality. It is worth reading the framework reference in your audit report each year to confirm it says what you expect.
For what an audit involves more generally, see How an Auditor Actually Works With Your Business in Singapore
How the framework choice affects your ACRA filing
The framework determines your XBRL route. Companies applying SFRS, SFRS(I) or IFRS file in XBRL, either Full or Simplified depending on size. Companies using accounting standards other than those file a PDF copy only.
Within XBRL, the framework has to be selected correctly when tagging, and selecting the wrong one is one of the more common filing errors. The full XBRL category table and the S$500,000 test that separates Full from Simplified are at XBRL Filing in Singapore: Full vs Simplified, and How It Connects to Your Audit
Changing framework: when it is worth it, and what it costs
Moving between frameworks is a transition, not a switch of a setting. It requires restating comparatives, and it produces a set of transition adjustments that have to be explained. That work happens once, and then the annual saving repeats.
The cases where a change is usually worth considering:
- A company comfortably inside the size thresholds that has been applying full SFRS by inheritance rather than by decision
- A company whose disclosure burden has grown out of proportion to the size of its operations
- A company that has grown past the thresholds and must move up to full SFRS, which is not optional
- A company preparing to report into an international group or to raise capital, where SFRS(I) is likely to be required
The cases where it usually is not: a company close to the thresholds and growing, which will have to move back up within a year or two, and a company mid-way through a financing process, where changing the basis of preparation invites questions from the counterparty at the worst moment.
Discuss any change with your auditor before committing to it, because the transition adjustments and restated comparatives will be audited.
 Frequently asked questions
What does SFRS stand for?
Singapore Financial Reporting Standards, the accounting standards under which Singapore-incorporated companies prepare their financial statements. They are closely aligned with International Financial Reporting Standards.
What is the difference between SFRS and SFRS(I)?
SFRS(I) is the Singapore framework that is identical in substance to IFRS, allowing a company to state compliance with International Financial Reporting Standards. It is applied by listed companies and by companies that need IFRS-compliant statements, typically for an international group or investor.
Who can use the SFRS for Small Entities?
An entity that is not publicly accountable, publishes general purpose financial statements, and meets at least two of three criteria: total annual revenue not more than S$10 million, total gross assets not more than S$10 million, and not more than 50 employees.
Is SFRS for Small Entities the same as the small company audit exemption?
No. The thresholds are the same figures, but they are separate tests under separate rules. Audit exemption comes from the Companies Act and has its own conditions, including about consecutive financial years and group position. A company can qualify for one and not the other.
Does using SFRS for Small Entities mean a lighter audit?
It means less disclosure for the auditor to check, not a lower standard of audit. The auditor still tests whether the financial statements give a true and fair view in accordance with the framework named in the report.
What does publicly accountable mean?
An entity is publicly accountable if its debt or equity instruments are traded in a public market, or if it holds assets in a fiduciary capacity for a broad group of outsiders as one of its primary businesses, which captures banks, insurers and certain fund managers regardless of size.
Can I change reporting framework?
Yes, but it is a transition rather than a setting. Comparatives must be restated and the transition adjustments explained and audited. Discuss it with your auditor before committing, and avoid changing mid-way through a financing process.
How does the framework affect XBRL filing?
Companies applying SFRS, SFRS(I) or IFRS file in XBRL, Full or Simplified depending on size. Companies using other accounting standards file a PDF copy of the financial statements only.
Not sure which framework your accounts are actually prepared under?
It is written in the first note to your financial statements and in your audit report. If the answer surprises you, it is worth a conversation. AG Singapore prepares and audits financial statements under all three frameworks. Check out AG’s financial reporting services and audit services.

 or SFRS for Small Entities: Which Reporting Framework Your Company Must Use)